My first salary was small. I promised myself I would save half of it. By the nineteenth of the month, I was eating instant noodles and borrowing bus fare from a coworker. That was twelve years ago. I am not a natural saver. I am a person who learned, slowly and with many mistakes, how to save money effectively from salary without turning my life into a spreadsheet.
This article is not about extreme frugality. It is about one question. Why does your salary rise but your savings stay flat? If you have ever felt that money disappears before you can catch it, these ideas are for you.
Quick Answer: How do I save money effectively from my salary?
Move your savings out first, on payday, before you spend anything. Ten percent is enough to start. Put it in a separate account at a different bank. Then forget it exists.
Why Does Money Never Feel Like Enough to Save?
Here is something I noticed after years of getting this wrong. Most people try to save what is left over at the end of the month. That sounds logical. It also fails almost every time.
When I treated savings as leftovers, the leftovers were always crumbs. There was always one more dinner, one more pair of shoes, one more thing that felt urgent. The money that remains never remains.
A friend of mine, a nurse with two kids, said something that stayed with me. She said, I do not have a spending problem. I have an ordering problem. She was right. The order in which money moves decides everything.
So the first shift is not a budgeting app. It is a sequence. Money for saving should move before money for spending, not after.
How Do You Split Your Salary on Payday?
I started doing this about six years ago, and it changed my household. The night before payday, or the morning of, I sit with a cup of tea and split the incoming salary into three places, in this exact order.
First, the untouchable. Ten percent goes straight to a separate account the same day. Not twenty. Not thirty. Ten. I learned that a percentage I can actually keep beats a percentage I abandon by day ten.
Second, the fixed life. Rent, utilities, transport, phone. Numbers I already know, so I write them down once and stop thinking about them.
Third, the flexible life. Food, clothes, small joys. Whatever is left is genuinely free to spend, and I spend it without guilt.
The magic is not in the math. The magic is that saving stopped being a decision I make every day. It became a thing that already happened.
If you want to go deeper on the habits behind this, From Debt to Wealth by Owen Pierce asks a question that stopped me cold. Why do I make money every month and still have nothing left? The book walks through the patterns that keep people circling, like spending more as income rises and mistaking expensive things for wealth. It pairs well with the payday sequence above.
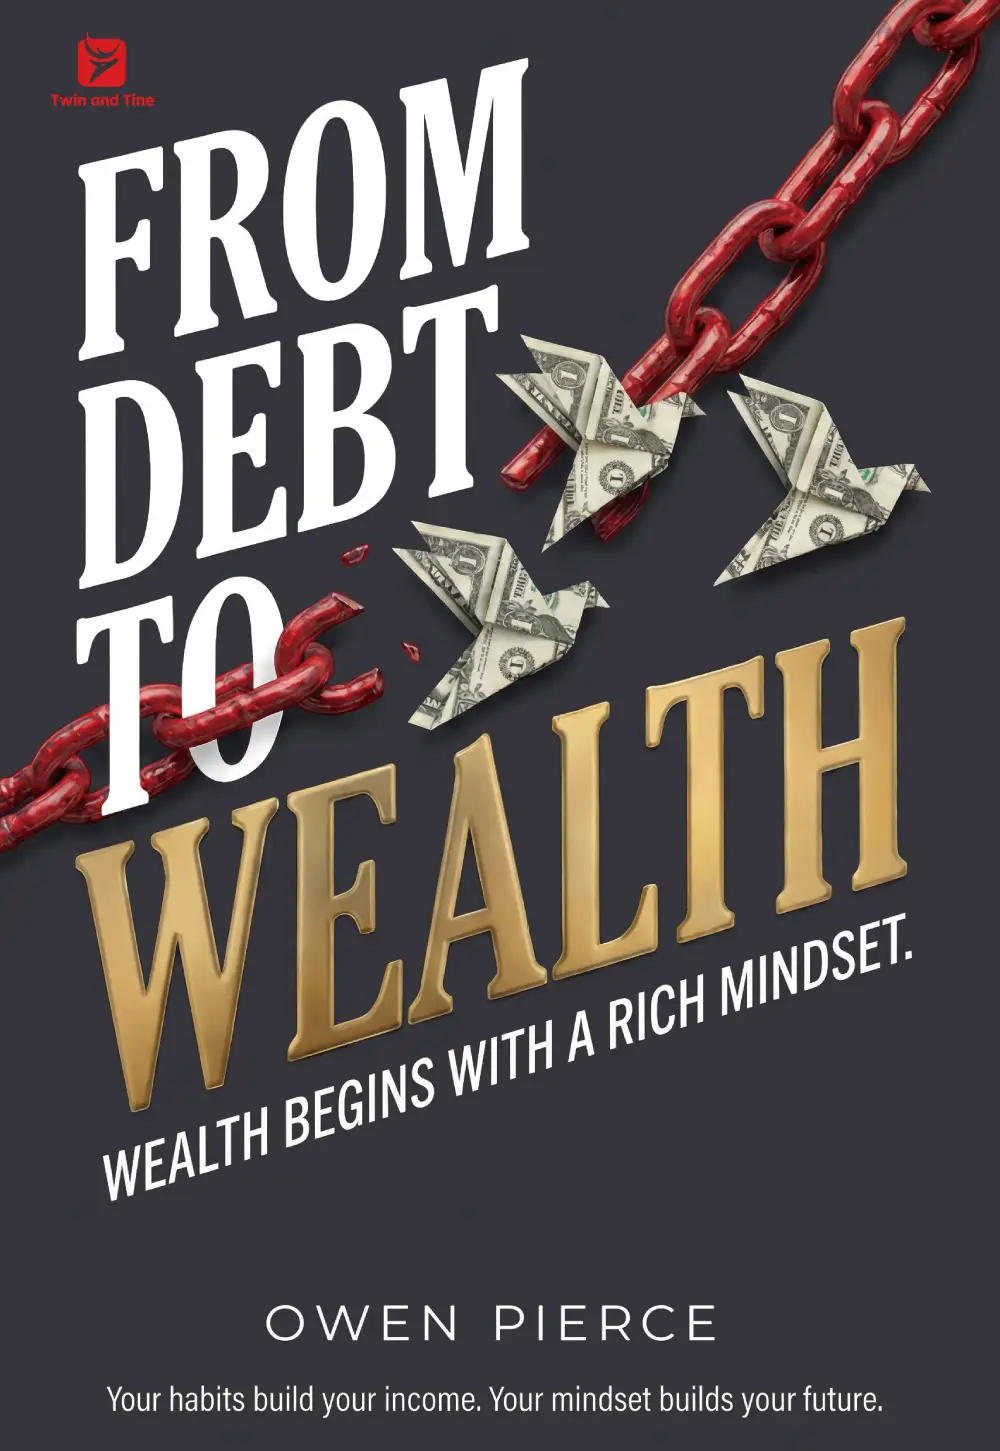
From Debt to Wealth
Owen PierceYour paycheck comes in. The bills go out. And somehow, you’re back at zero again.
Learn why earning more does not always create financial progress—and what has to change before your money starts working differently.
Should You Still Save When Your Salary Is Low?
Yes. But the amount should be almost embarrassing.
There was a season when my income dropped and I could only put away a tiny amount each month. Someone laughed. He said, what is that? A lunch? I understood his point. I also noticed something he did not. After twenty months, I had a small cushion and, more importantly, I still had the habit. When my income recovered, the habit was already sitting there, waiting.
The habit matters more than the amount. A tiny automatic transfer keeps the muscle alive. Stop the transfer, and restarting is ten times harder than it was the first time.
What About the Money You Always Want to Spend?
You will still want things. That is not a character flaw. I want things constantly.
Here is what helped me. When I see something I want, I write it on a note on my phone with the date. If I still want it after two weeks, I buy it. If I have forgotten about it, I delete the note.
I once waited two weeks for a rice cooker. I bought it on day fifteen and used it for years. I also waited two weeks for a coat I was sure I needed. By day six I could not remember why. That coat would have cost real money. The note cost me nothing.
What If Your Family Does Not Follow the Plan?
This is the part nobody warns you about. Saving is easy when you live alone. It gets complicated when someone else is spending from the same pot.
What finally worked was not a rule. It was a shared goal with a name. We called it the trip money. Every month, we both put something into a jar account for a trip. She could see it growing. I could see it growing. The argument stopped being about restriction and became about a beach.
If your partner spends differently than you, look for one shared thing worth saving for. One shared goal beats a hundred rules.
Does Saving Make Life Miserable?
Only if you save in a way that punishes you.
I tried a strict month once. No coffee, no snacks, no small pleasures. I lasted eleven days and then spent more in one weekend than I had saved in three weeks. Punishment budgets break. They always do.
Now I keep a small line in the flexible section called joy money. It is real money, and I am allowed to waste it. Knowing it exists makes the rest of the plan easier to keep.
Where Should the Saved Money Actually Go?
A separate account. Not your daily account. Not the one linked to your phone payment apps.
When my savings sat in my everyday account, they were visible and reachable at every meal. I spent them without meaning to. When I moved them to a different bank with no card attached, the money simply left my attention. Out of sight, out of temptation.
I also stopped checking the balance daily. Looking at it every day made me either anxious or proud, and both feelings led to spending. Now I look once a month.
FAQ
How much of my salary should I save?
Start with ten percent. It is small enough to keep and big enough to matter over time. Increase it when your income grows.
What if I cannot save ten percent?
Save something. Even a tiny amount keeps the habit alive. The amount matters less than the consistency in the first year.
Should I save before or after paying bills?
Before. Move the savings out on payday, then pay bills. If you wait until after, there is never anything left.
Where should I keep my savings?
A separate account at a different bank, ideally without a card attached. Friction helps.
What if my partner spends differently?
Find one shared goal worth saving for. One goal beats a hundred rules. Let everything else be loose.
One Last Thing
I did not learn to save because I love numbers. I learned because of one night when someone I love got sick, and I stood in a hospital corridor calculating whether I could afford the medicine. I could. Barely. That barely stayed with me.
Saving is not about being rich. It is about the moment when something goes wrong and you can say, okay. We can handle this. That sentence is worth more than any interest rate.
You do not need to be good with money. You need a sequence, a small automatic amount, and one reason that matters to you. Start with your next payday.
References
- Pierce, Owen. From Debt to Wealth.
- Collins, J. L., & Vigna, B. The Index Card. Portfolio, 2016.
- Thaler, R. H., & Sunstein, C. R. Nudge. Yale University Press, 2008.