I used to think I was bad with money. Then I realized something uncomfortable. I never actually had a system. I had a vague intention to spend less, and a spreadsheet I abandoned by February 14th every single year.
The turning point came when my wife and I sat down to plan a modest kitchen renovation. We had the income. We had the savings account. But we could not tell you where the money went each month. It just evaporated. That is when I started hunting for books like Get Good with Money, looking for a clear monthly budget system that a normal, tired, working parent could actually follow.
I did not want theory. I wanted a process. Here is what I found.
Why Does My Budget Always Fall Apart by Week Three?
The problem is rarely discipline. It is design. Most budgeting advice assumes you are a robot who can log every coffee purchase for the rest of your life. I am not. You are probably not either.
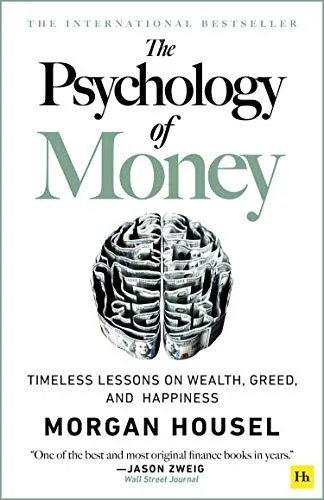
The deeper issue is that we treat money as a math problem. But money is a behavior problem. Morgan Housel makes this point beautifully in The Psychology of Money. He argues that people make financial decisions at the dinner table, not on spreadsheets. Our history, our ego, our stress levels, they all scramble the numbers.
So why does your budget fall apart? Because it was built to track the past, not to guide the future. A clear monthly budget system does not just record what you spent. It decides, before the month begins, what you are allowed to spend. That shift, from tracking to deciding, changed everything for me.
I also noticed that I was budgeting for an idealized version of myself. The version who meal preps on Sundays and never impulse buys. That person does not exist. So the budget failed. It was not a failure of willpower. It was a failure of honesty.
How Do I Build a Monthly Budget System That Actually Sticks?
Stop trying to track every penny. Start giving every dollar a job before the month starts. This is the core idea behind a clear monthly budget system, and it is the reason I finally stopped living paycheck to paycheck.
Here is what worked for us. On the last day of each month, we open our checking account. We list every bill that is due in the next thirty days. Rent, utilities, insurance, subscriptions. Then we list our two variable categories, groceries and gas. We give those categories a fixed number. Not a hope. A number.
Then comes the part that changed our life. We take the money that is left, and we move it. Immediately. Into a savings account at a different bank. Not a savings account attached to our checking account. A separate bank entirely. The friction of moving it back is enough to stop us from doing it casually.
Here is a dialogue example from our own house. My wife asked me, “Did you move the surplus?” I said, “Yes, three hundred dollars.” She said, “Good. Now we cannot eat out until the first.” That is the system. It is not glamorous. It is not complicated. It works.
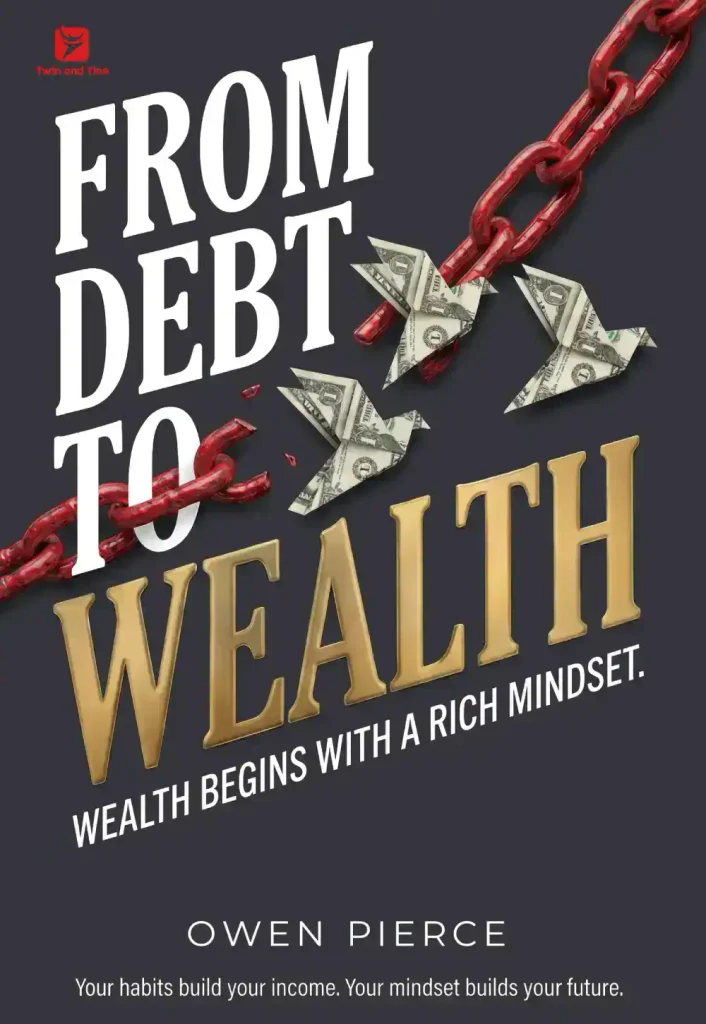
For a deeper dive into this exact philosophy, I recommend Owen Pierce’s From Debt to Wealth. The book is a practical guide to breaking the paycheck-to-paycheck cycle, and it hammers home one essential truth. Wealth is not a reward for hard work alone. It is compensation for how you think about money. Pierce shows you how to escape living paycheck to paycheck by building real assets instead of flashy liabilities.
The 72-Hour Money Pause: One Simple Tool
I want to give you one specific framework today. I call it the 72-Hour Money Pause. It is the single most effective tool I have for keeping our monthly budget system intact.
Here is how it works. Any time you feel the urge to make a non-essential purchase over fifty dollars, you do not buy it. You write it down instead. On your phone, on a sticky note, wherever. Then you set a timer for 72 hours.
When the timer goes off, you revisit the item. Do you still want it? Do you still need it? In my experience, about 70 percent of those urges vanish within three days. The other 30 percent, you evaluate against your monthly budget categories. If there is room, you buy it. If there is no room, you wait until next month.
This pause does two things. It breaks the dopamine loop that drives impulse spending. And it forces you to be intentional about every discretionary dollar. My wife and I use it constantly. She wanted a new kitchen appliance last month. She wrote it down. Three days later, she realized she did not actually have a place to store it. Crisis averted.
This tool aligns perfectly with what JL Collins writes in The Simple Path to Wealth. He warns that complex investments and complicated financial products exist only to profit the people who sell them. The simple path is always more powerful. The 72-hour pause is the simplest possible defense against the consumer machine.
What About the First Month? Expect It to Be Ugly
Here is the honest truth. Your first month on a clear monthly budget system will be uncomfortable. You will discover things about your spending that you do not like. I discovered I was spending over two hundred dollars a month on lunches. Not fancy lunches. Just average, forgettable sandwiches and salads.
That discovery was not a failure. It was the point. You cannot fix what you cannot see.
The first month, just track. Do not try to change everything. Use the 72-hour pause for new purchases. But let your regular habits flow. See where the money actually goes. Then, in month two, you start assigning those categories their fixed numbers.
I remember sitting at our kitchen table in month two, staring at our grocery number. I had set it at four hundred dollars. My wife looked at me and said, “That is too low. We will fail by the second week.” She was right. We adjusted it to five hundred and fifty. We came in at five hundred and thirty. The feeling of hitting that number, even by a little, was better than any purchase I have ever made.
How This Works for Different Income Levels and Habits
You might be thinking, this is fine if you have extra money. What if you do not?
The system still works. It just gets tighter. When we were at our lowest point, our budget had zero slack. Every category was exactly at the minimum. But we still moved the surplus, even if the surplus was only twenty dollars. That twenty dollars a week added up to eighty dollars a month. Over a year, that is nearly a thousand dollars. It was the foundation of our emergency fund.
For people who are drowning in debt, the priority shifts. Before you do anything else, you eliminate the bad debt. Pierce covers this extensively in From Debt to Wealth. He makes a crucial distinction between good debt, which builds assets, and bad debt, which funds consumption. Credit card debt is almost always the bad kind. It is the anchor that keeps you living paycheck to paycheck.
The order of operations for us was simple. First, we cut the bad debt. Second, we built a one-month emergency fund. Third, we started investing. That sequence took us almost two years. But it worked because we had a clear monthly budget system that gave us permission to say no to ourselves.
Frequently Asked Questions
Do I need a specific app to maintain a clear monthly budget system?
No. We used a simple notebook for the first year. The tool does not matter. The weekly check-in matters. You need to sit down, once a week, and look at your categories. That is the system.
Which book is best for someone who wants a clear monthly budget system but hates reading about investing?
From Debt to Wealth is the most practical starting point. It focuses heavily on escaping the paycheck-to-paycheck cycle and building sustainable savings. It does not assume you already know anything about finance.
How is this different from just using a budgeting app?
Apps track your spending. A system changes your behavior. The app tells you what happened. The system tells you what is allowed to happen. The difference is subtle but huge. You need the behavioral side, which is why books like The Psychology of Money are so valuable.
I have tried budgeting before and failed. Why would this time be different?
Because this time you are not relying on willpower. You are relying on structure. You are moving money out of reach. You are pausing before purchases. The system does the heavy lifting, not your self-control.
One Last Thing
I remember the night we moved our first real surplus into the separate savings account. It was seventy-five dollars. We sat on the couch in silence for a moment. My wife whispered, “We actually did it.” It was not a fortune. It was not a milestone anyone else would notice. But it was proof.
Proof that we were not broken. Proof that we could control our money instead of the other way around. If you are still living paycheck to paycheck, I want you to know something. You are not bad with money. You just do not have a system yet.
Start this month. Use the pause. Give every dollar a job. Move the surplus out of reach. And read a book that rewires how you think about wealth. The path is simple. It is not easy. But it works.