I was standing in the grocery store last week, doing the math on my phone. Not the fun kind. The kind where you add up the total before you get to the register, because you are not entirely sure the card will go through. My child was asking for the cereal with the cartoon on the box. I said no without even looking at the price. That night I lay in bed thinking: I have a job. I have a roof. Why do I still feel like everything could fall apart any second?
That gap between the numbers and the feeling is where the real work lives. Learning how to create financial security mindset changed how I slept at night. It did not change my salary. It changed what I did with the salary.
Financial security is not the same as having money. It is the confidence that your situation is under control and your future is protected. Some days I have that confidence. Some days I do not. The goal is to build it on purpose, one small decision at a time.
Quick Wins for Today
- Write down one number: your monthly must-pay total.
- Set an automatic transfer for the day after payday.
- Name your emergency fund something real, like “Car Dies Fund.”
- Pick one subscription to cancel this week.
- Say your money worry out loud to one person.
Why Does Financial Security Feel So Far Away for Parents?
Here is what nobody tells you. The worry is not really about math. It is about control. When my child needed stitches on a Tuesday, I did not think about interest rates. I thought, can we handle this without panic? That is the question underneath every money stress moment.
Most parents I know are doing the right things. We pay bills. We skip the fancy coffee sometimes. And still the worry sits there, because there is no plan holding it all together. A plan turns chaos into a list. A list feels smaller than a feeling.
Many parents find that the anxiety fades when they can answer three simple questions. What comes in? What must go out? What is left? If you cannot answer those, your brain fills the gap with fear. Mine did for years. So we started there.
How to Create Financial Security Mindset Step by Step
I started with a budget that reflected what we actually cared about. Family. A little travel. Not stuff. When your spending matches your values, you stop fighting yourself. Budgeting is not restriction. It is giving every dollar a job.
Then we built an emergency fund. Ours started tiny. Every medical bill, every car repair, every surprise used to go on a card. Now it comes out of a separate account we do not touch. A starter fund should eventually cover three to six months of living expenses. Three months felt impossible. So we did one month first.
Debt came next. High interest debt is the heaviest backpack you can carry. We used the snowball method, smallest balance first, because I needed the emotional wins. Some people prefer paying the highest rate first. Both work. Pick the one you will actually finish.
Here is the part I got wrong for years. I treated savings as whatever was left over. There was never anything left over. Now we treat savings as a mandatory expense, like rent or a car payment. It comes out automatically. It is not a decision anymore. It is just a bill we pay to our future selves. If your employer deducts it from your paycheck before taxes, even better. That lowers the income taxes owed on your salary.
The Payday Split Ritual
We made up a name for our system. The Payday Split Ritual. It sounds silly. It works.
On payday, before I buy anything, I split the money into four buckets. Bills. Emergency fund. Retirement. Then, and only then, spending. The order matters. Fun money comes last, and it is still there. It is just smaller than it used to be.
You can automate this. Have your salary direct-deposited, then schedule an automatic transfer to savings for the same day. The money never sits in checking long enough to tempt you. Out of sight, out of spending range.
Some parents also use tax-deferred retirement accounts as a kind of guardrail. Money in those accounts is harder to spend on impulse, because pulling it out early can trigger income taxes and a penalty if you are under a certain age. That friction is a feature. It protects you from your late-night self.
Do You Have to Diversify Everything at Once?
No. And you should not try. My first year I had one fund and one retirement account. That was enough.
Diversifying matters because putting everything in one basket increases the risk of losing it all. Proper asset allocation considers your age, your risk tolerance, and whether you need your money to grow or to produce income. Younger parents can usually take more risk. Closer to retirement, less. But you do not need to figure this out alone or all at once.
| Life Stage | What to Focus On | Simple First Move |
|---|---|---|
| Just starting | Emergency fund | Automate a small weekly transfer |
| Mid-career | Debt + retirement | Increase contribution 1% |
| Kids in school | Insurance check | Review health and life coverage |
| Near retirement | Asset mix | Reduce risk, rebalance yearly |
Insurance is the quiet piece. Health, disability, and life coverage protect your family from one bad month turning into years of recovery. I put off reviewing ours for two years. When I finally did it, I found we were overpaying and undercovered at the same time.
What Does It Really Mean to Be Financially Secure?
For me, it means not flinching when the mechanic calls. It means my child can sign up for the school trip without me checking the account first. That is it. That is the whole feeling.
Estate planning sounds heavy. At its core it is one question. If something happens to me, is my family okay? A simple will, named beneficiaries, and a folder your partner knows about covers more than most people have.
But protection is not the same as progress. If you’ve done the budget, automated the transfer, and built a small buffer—and you still wonder why more income doesn’t turn into more freedom—this next resource is for you.
Does your money ever feel like this?
“I just got paid. Where did it all go?”
“I earn more than I used to—but I still don’t feel ahead.”
“I know I should save, but there’s never enough left.”
If those lines feel familiar, the problem may not be your budget. It may be the system underneath it.
Why do I make money every month—and still have nothing left?
Earning more and building wealth are not the same thing. From Debt to Wealth helps you see income, spending, skills, time, and assets as one system—and change the patterns that keep money moving through your hands instead of staying in your life.
- Shift the mindset that confuses long hours with progress and income with wealth.
- Build income beyond trading more hours for more pay.
- Replace paycheck-draining habits with ones that build real freedom.
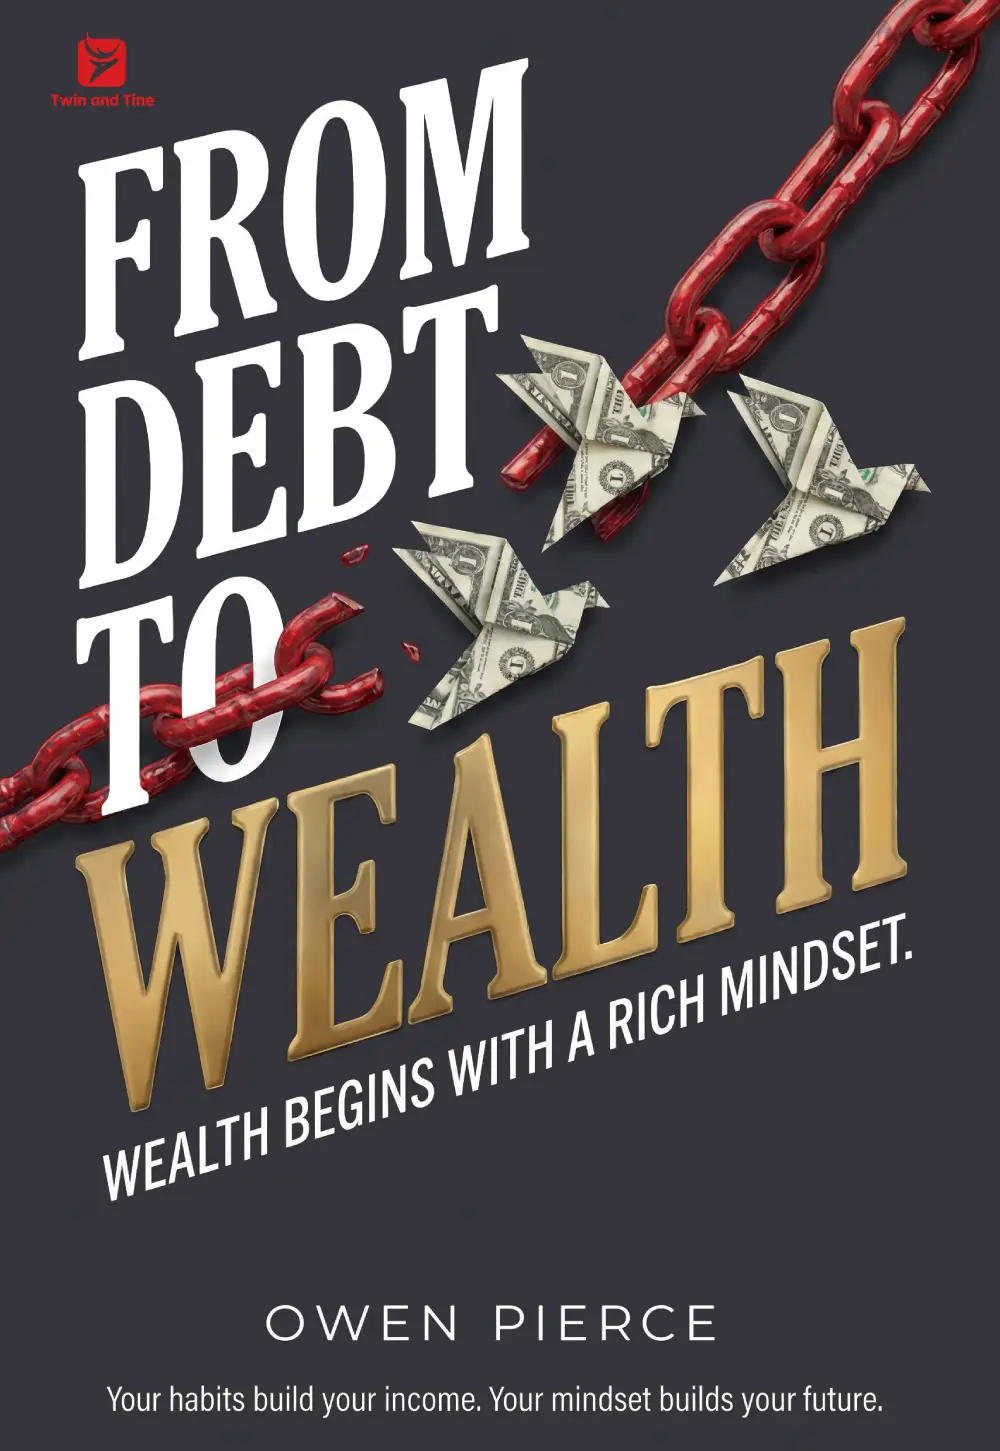
From Debt to Wealth
Owen PierceYour paycheck comes in. The bills go out. And somehow, you’re back at zero again.
Learn why earning more does not always create financial progress—and what has to change before your money starts working differently.
If you’re still deciding whether the problem is your budget, your debt, or your mindset, the FAQ below may help.
FAQ
Q: How do I create a financial security mindset when I am living paycheck to paycheck?
A: Start with one number: your monthly must-pay total. Then automate one small transfer, even a few dollars, the day after payday. The habit matters more than the amount at first.
Q: What is the fastest way to feel less money stress?
A: Know what comes in, what must go out, and what is left. That clarity alone reduces the panic. Then build one small buffer, even a starter emergency fund.
Q: Should I pay off debt or save first?
A: Many parents do both, with a small emergency fund first and then debt payoff. Pick the method you will actually stick with, snowball or highest rate first. Consistency beats math perfection.
Q: Do I need a financial advisor to build security?
A: Not always. Many people start with automatic savings, a simple budget, and a retirement account through work. If your situation is complex, a fee-only advisor can help, but it is not required to begin.
Q: How long does it take to feel financially secure?
A: It varies. Some parents feel a shift within a few months of consistent habits. The feeling grows as your buffer grows. Progress is not linear.
One Last Thing
That grocery store moment still happens sometimes. I still do the math on my phone. But the kitchen table is quieter now. Not silent. The bills still come. But I know where the money goes, and I know we will handle it. That knowing is the whole thing.
References
- Consumer Financial Protection Bureau. (n.d.). An essential guide to building an emergency fund. Retrieved from consumerfinance.gov.
- U.S. Department of Labor. (n.d.). Savings fitness: A guide to your money and your financial future. Retrieved from dol.gov.
- Ramsey, D. (2013). The Total Money Makeover. Thomas Nelson.