We were sitting in the car outside a grocery store when my wife asked the question I had been dodging for months. So how do you actually invest fifty dollars to five thousand without losing it all?
I laughed. Not because the question was funny. Because I had been investing for six years and still felt like I was guessing half the time. My first attempt started with two hundred dollars in a brokerage account I opened at midnight, half-asleep, clicking buttons I did not understand.
That account lost thirty percent in three months. Not because the market crashed. Because I bought things I could not explain to another human being.
So this is not a lecture. It is the walkthrough I wish someone had given me.
Quick Answer: How do I invest between $50 and $5000?
Split your money into two buckets. Most of it goes into one boring broad market fund. A small slice goes into something you want to learn about. Automate the boring bucket. Do not touch it.
What Does the Amount Actually Change?
Fifty dollars and five thousand dollars are two completely different psychological projects.
When I had fifty dollars, my problem was access. Many platforms charge fees that eat small amounts alive. A five dollar trade fee on a fifty dollar position is a ten percent loss before the stock moves at all.
When I had five thousand, my problem was different. I froze. Every choice felt heavy. I once spent two weeks deciding between two index funds and missed a market run by hesitating.
The amount changes the emotion, not just the math. Start by naming which emotion you are dealing with.
Why Does Investing $50 Feel Harder Than $5000?
Because small amounts make us impatient. I remember thinking, what is the point of fifty dollars growing at seven percent a year? That mindset pushed me toward risky bets. I wanted fifty to become five hundred fast.
It did not. It became forty-one.
A friend of mine had the opposite reaction. She saved three thousand and then sat on it in a checking account for two years because she was terrified of doing the wrong thing. Inflation quietly ate maybe one hundred and fifty dollars of her purchasing power. She never saw it happen.
Both reactions come from the same place. We treat investing like a test we might fail.
The Two-Bucket Method
I made this name up. It is not fancy. But it saved me from myself.
Bucket one is your boring money. This is where most of your amount goes. For me it is a broad market index fund. One fund. That is it. I do not check it weekly. I check it quarterly, usually on a Saturday with coffee.
Bucket two is your learning money. This is a small slice, maybe ten percent of your total. I use it to buy one company I actually understand and follow. A coffee chain. A software tool I use daily.
The rule is simple. Bucket two exists so bucket one stays boring. When I want to chase something exciting, I do it in bucket two. Then I stop.
| Total Amount | Boring Bucket (90%) | Learning Bucket (10%) |
|---|---|---|
| $50 | $45 | $5 |
| $500 | $450 | $50 |
| $2000 | $1800 | $200 |
| $5000 | $4500 | $500 |
What Was I Thinking on My First Buy?
I was scared. My hand hovered over the confirm button for maybe ninety seconds. Then I thought about my father, who kept everything in a savings account his whole life and told me the stock market was gambling.
He was not wrong to be cautious. He was wrong to think caution means doing nothing forever.
My first real purchase was three hundred dollars into a total market fund. Nothing happened for two months. Then it went up twelve dollars. I felt absurdly proud of that twelve dollars.
How Do You Decide Where the Money Actually Goes?
Ask three questions before any purchase.
- Can I explain this investment to a friend in one sentence?
- Would I still hold it if it dropped forty percent?
- Do I need this money within three years?
If any answer is no, wait. I have broken this rule exactly four times. All four hurt.
One more thing. Fees matter more than most beginners realize. A fund charging one percent annually versus one charging zero point zero five percent sounds trivial. Over twenty years on five thousand dollars, that gap can quietly swallow hundreds. I check the expense ratio before anything else now. It takes thirty seconds.
If you want a closer look at why money leaks out even when you are earning, From Debt to Wealth by Owen Pierce asks the question that sits underneath all of this. Why do I make money every month and still have nothing left? The book walks through the habits that keep people circling, like spending more as income rises and mistaking expensive things for wealth. It pairs well with the two-bucket idea, because both are about noticing where the money actually goes.
Should I Wait for a Dip?
I tried this once. I had eight hundred dollars ready and told myself I would buy after the next big drop. The market rose eleven percent while I waited. I bought in higher than if I had just gone in that day.
A friend told me something that stuck. Time in beats timing, and I say that as a nurse who hates clichés.
She is right. Most of my gains came from money that sat there for years doing nothing visible.
One Quiet Reminder
The best investment decision I ever made was not a stock pick. It was setting up an automatic transfer of seventy-five dollars every two weeks. I stopped deciding. The decision fatigue disappeared.
For fifty dollar starters, that might be ten dollars a week. For five thousand, maybe two hundred a month spread across a year. The number matters less than the rhythm.
FAQ
Can I really start investing with just fifty dollars?
Yes. Many platforms now offer fractional shares and no commissions. The amount matters less than starting the habit.
Should I pay off debt before investing?
If your debt has a high interest rate, pay it down first. If it is low, do a little of both. Doing nothing is the worst option.
What is the safest thing to invest in as a beginner?
A broad market index fund. It holds hundreds of companies, so you are not betting on one.
How often should I check my account?
Quarterly is enough. Checking daily makes you want to do something, and doing something is usually worse than doing nothing.
What if the market drops right after I invest?
Then your next automatic transfer buys more shares at a lower price. Drops work in your favor when you are investing regularly.
One Last Thing
That night in the car, I did not have a clean answer for my wife. I still do not. But the next morning we opened an account together and moved two hundred and fifty dollars into one boring fund.
It felt small. It was enough.
References
- U.S. Securities and Exchange Commission. “Compound Interest Calculator.” Investor.gov.
- Bogle, John C. The Little Book of Common Sense Investing. Wiley, 2017.
- Pierce, Owen. From Debt to Wealth.
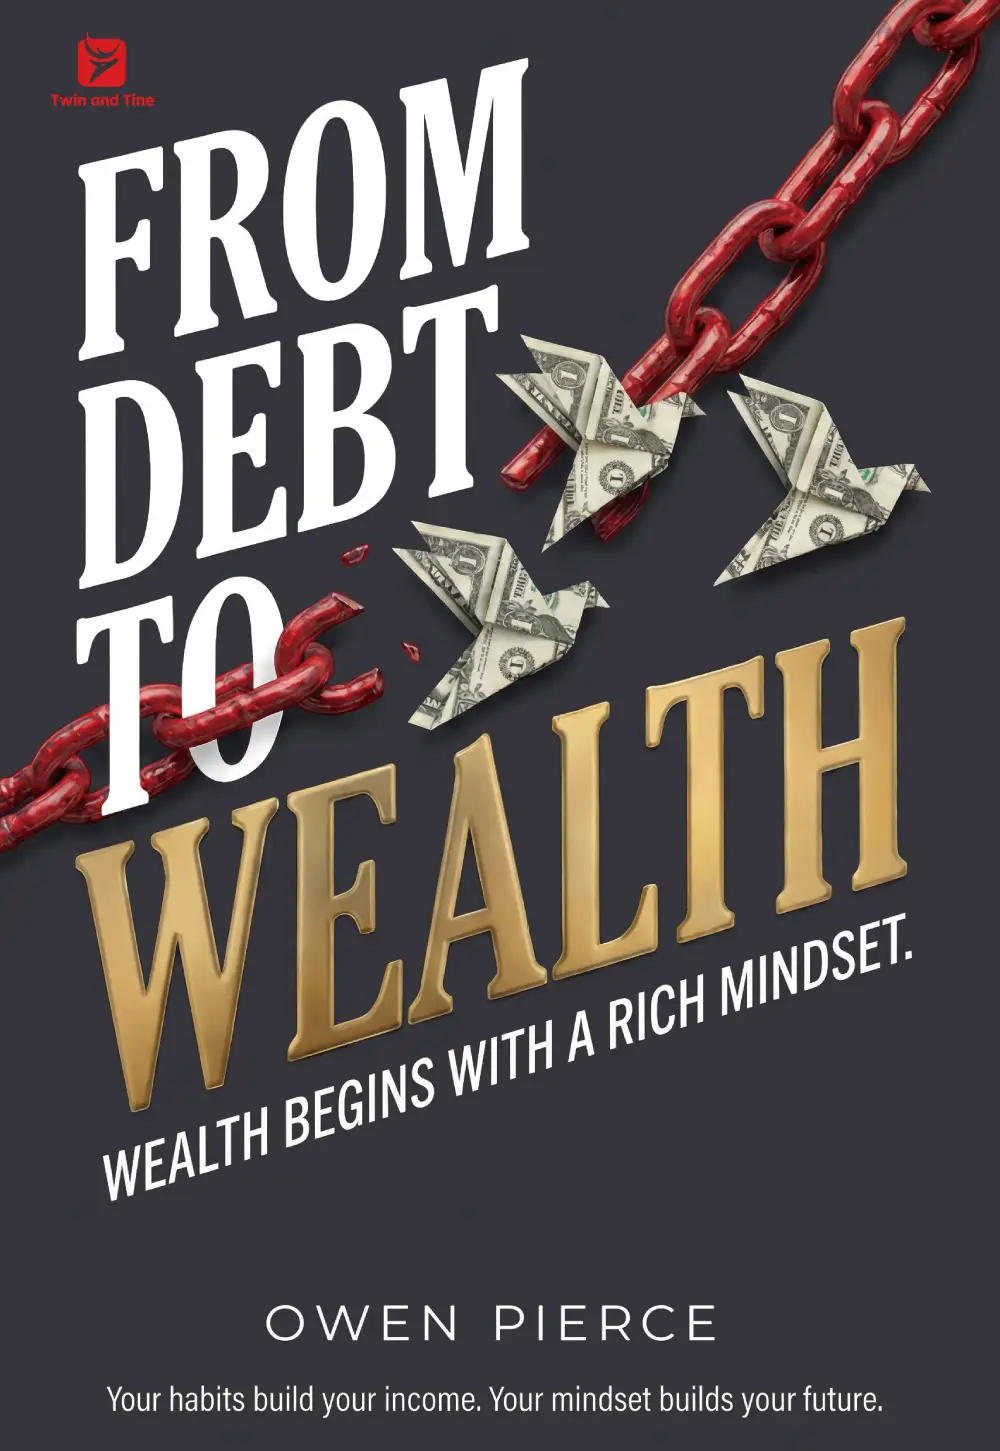
From Debt to Wealth
Owen PierceYour paycheck comes in. The bills go out. And somehow, you’re back at zero again.
Learn why earning more does not always create financial progress—and what has to change before your money starts working differently.