A few years ago I sat in my car in a grocery store parking lot and counted coins in the cup holder to see if I could afford both milk and gas. I was thirty-four. I had a job. And I had no idea how to save money and invest wisely, because nobody in my family ever talked about money except to say we did not have any.
That afternoon, I decided I was done waiting to feel qualified. I started reading. I started asking blunt questions. And slowly, over about four years, the numbers in my account stopped being a source of dread and started being a source of quiet confidence.
Quick Answer: How do I start saving and investing with no head start?
Move your savings out first, on payday, before you can spend it. Pay down high-interest debt. Open one simple index fund and automate it. Then leave it alone.
Where Did the Money Actually Go?
Most advice starts with budgets. I think budgets come second. First you have to see the truth without flinching.
For one month, I wrote down every single thing I spent. Not to judge it. Just to look at it. The result embarrassed me in a useful way. Three food deliveries a week. A subscription I had forgotten existed since a free trial in March. Two streaming services I could not tell apart.
The pattern was not recklessness. It was autopilot. Money left quietly, in small amounts, so I never felt the loss of any single purchase. That is how most leakage works. It hides in the ordinary.
So my first real step was not cutting anything. It was naming everything. Once the spending had names, the choices got easier on their own.
Why Does Saving Always Seem to Fail?
Here is something I wish someone had told me earlier. Saving what is left over at the end of the month is a plan that fails by design. There is never anything left.
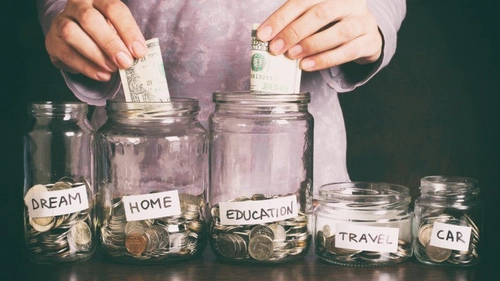
The fix is boring and it works. Move the savings out first, on payday, before you can spend it. Even a small amount. Twenty dollars. Then forget it exists.
I set up an automatic transfer the day after I get paid. It goes to a separate account at a different bank, one without a card attached to my wallet. Friction matters. If getting to the money takes three extra steps, I usually leave it alone.
The first month, I barely noticed the missing twenty. By month six, I had a small cushion, and a cushion changes how you sleep.
Pay Debt First, or Invest First?
This question kept me stuck for a whole year, which was itself the most expensive decision I made. So let me save you the year.
There is no universal answer. There is only math and feeling. If your debt carries a high interest rate, that rate is a guaranteed loss. If your debt is low and slow, putting a little into investing while you pay it down is fine.
What mattered for me was doing something. Doing nothing while I waited for the perfect order of operations cost me more than any imperfect choice would have.
Where Do You Actually Start Investing?
The honest answer is smaller and less glamorous than the internet makes it look.
Use the match. If your job offers a retirement match, that is free money. I left it on the table for years. That still stings.
Open one index fund. Not ten. One broad fund that holds hundreds of companies.
Automate it. Same amount, same day every month. Some months it drops. Some months it climbs. You stop checking weekly because checking weekly makes you want to do something, and doing something is usually worse than doing nothing.
The hardest skill in investing is sitting still.
Should I Listen to What Everyone Else Says?
A coworker once told me, with total confidence, that I should put everything into a stock he had researched for a weekend. I did not. It later dropped by half. He never mentioned it again.
The people worth listening to rarely sound certain. They say things like, this worked for me, and, your situation might be different. Anyone who promises you a formula is selling something.
The Three Envelope Method
I named my system after something my grandmother did with actual paper envelopes, and I adapted it for a bank app.
| Envelope | What It Covers | Rule |
|---|---|---|
| Today | Rent, food, bills, transport | Keeps the lights on this month |
| Tomorrow | Automatic savings transfer | Not for fun. Not for fear. For ordinary disasters |
| Later | Investing account | Do not touch for a decade or more |
Every payday, money moves into all three before I spend a cent on anything else. When I am tempted to pull from Later for a new couch, I remember that Later is not about the couch. It is about the version of me who is sixty and tired and deserves to rest.
Does the Approach Change With Age?
In your twenties, time is the advantage. Small amounts invested early do more work than larger amounts invested late.
In your thirties and forties, income usually rises, and so does life’s weight. This is when the Tomorrow envelope matters most.
In your fifties and beyond, the goal shifts toward protecting what you built. Less risk, more clarity.
The age matters less than the habit. A person who starts at fifty and stays consistent does better than a person who starts at twenty-five and quits every other year.
FAQ
How much money do I need to start investing?
As little as twenty-five dollars a month. The habit matters more than the amount in the first year.
Should I pay off debt or invest first?
If your debt has a high interest rate, pay it down first. If it is low, do a little of both. Doing nothing is the worst option.
What if I have no emergency fund?
Build one before you invest. Even a small cushion changes how you handle surprises. Start with one month of expenses.
Is it too late to start in my fifties?
No. Starting at fifty and staying consistent beats starting at twenty-five and quitting. Time matters, but consistency matters more.
What is the Three Envelope Method?
A simple system that splits your money into Today, Tomorrow, and Later. Every payday, money moves into all three before you spend on anything else.
One Last Thing
One evening last spring, someone asked me why I was reading a bank statement at the kitchen table with a cup of tea instead of a look of panic. I told them I was just checking on the three envelopes. They asked what that meant. I explained it the way my grandmother would have, with my hands, drawing invisible boxes in the air.
They nodded like it was the most normal thing in the world. And for them, I hope it will be.
References
- Consumer Financial Protection Bureau. “An essential guide to building an emergency fund.” consumerfinance.gov.
- U.S. Securities and Exchange Commission. “Saving and Investing: A Roadmap to Your Financial Security.” sec.gov/investor.
- Bogle, John C. The Little Book of Common Sense Investing. Wiley, 2017.